This week we want to discuss two developments that may help support stocks as we enter the fourth quarter: improving corporate earnings expectations and a historically favorable period in the election cycle.
Higher interest rates and energy costs remain headwinds. However, companies are entering earnings season with an encouraging outlook. Analysts expect S&P 500 earnings to have grown 29.5% year-over-year in the third quarter.
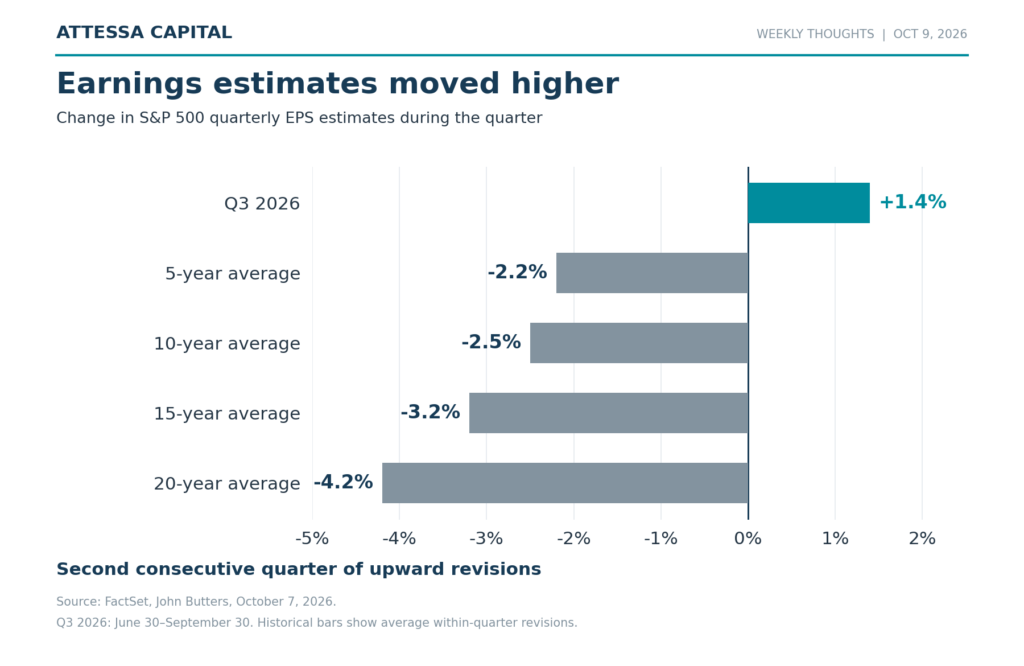
More interesting is the direction those expectations have been moving. Analysts usually lower their estimates as a quarter progresses. Over the past ten years, the average reduction has been 2.5%. This quarter, estimates increased by 1.4%—the second consecutive quarter of upward revisions.
The improvement extends beyond the quarter just completed. Between June 30 and September 30, analysts raised their full-year 2026 earnings estimates by 6.2%. We think this matters. Investors have a stronger expected earnings base to help offset the pressure higher interest rates can put on stock valuations.
The calendar also offers an encouraging backdrop. Since 1950, the S&P 500 or its predecessor has averaged a 6.6% fourth-quarter gain in midterm election years. That compares with averages of approximately 2.5% to 3.9% in the other years of the presidential cycle.
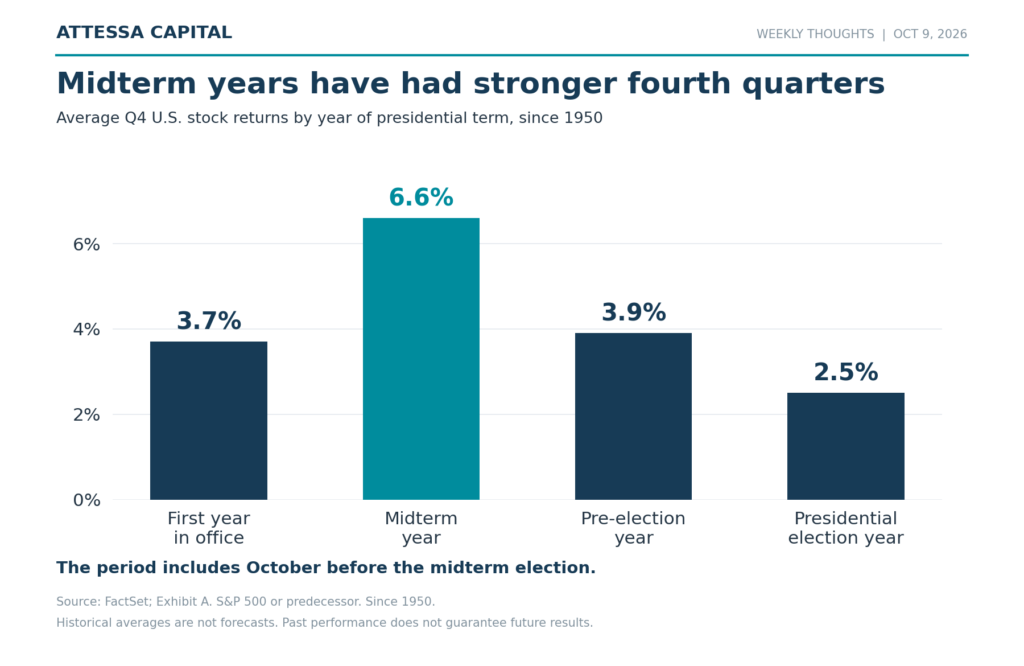
That period includes October before the election, and the historical average is not a forecast for this year. Still, it provides useful context as investors weigh political uncertainty alongside the earnings outlook.
Of course, higher expectations also raise the bar. Companies still need to turn those forecasts into actual profits, and disappointing results or another significant increase in interest rates could create renewed pressure.
For now, we believe improving earnings expectations provide a reasonable basis for a constructive outlook. The historical fourth-quarter pattern adds context, but earnings and valuations will carry more weight in our investment decisions than the election calendar.